S Harish Chandan
November 3, 2026
Market Closing Snapshot: Indian Stock Market Post-Market Analysis – 03 Nov 2026
Tuesday, 03 November 2026
| Index | Closing Level | Change | % Change |
| NIFTY 50 | 23,810.85 | +370.05 | +1.58% |
| SENSEX | 76,917.85 | +1,225.07 | +1.62% |
| BANK NIFTY | 55,540.05 | +537.85 | +0.98% |
| NIFTY MIDCAP 100 | 58,596.25 | +612.85 | +1.06% |
| NIFTY SMALLCAP 250 | 17,061.65 | +70.65 | +0.42% |
Our observation: The rally was led by large-cap stocks, financials and consumer-facing companies. Midcaps participated reasonably well, but smallcaps remained relatively subdued. The difference matters. A rising NIFTY has not meant that the entire market is experiencing an equally strong recovery.
Highest Gainers and Losers
NIFTY 50 – Top Gainers
| Company | % Change |
| BSE Ltd | +5.03% |
| Nestlé India | +4.47% |
| Tata Consumer | +4.29% |
| Asian Paints | +3.99% |
| Bharti Airtel | +3.77% |
NIFTY 50 – Top Losers
| Company | % Change |
| Power Grid | -3.04% |
| SBI | -1.70% |
| ONGC | -1.13% |
| Adani Enterprises | -0.84% |
| Tata Steel | -0.49% |
Broader NSE Market – Notable Gainers
| Company | % Change |
| Balrampur Chini Mills | +10.22% |
| Marico | +8.23% |
| Trident | +7.61% |
| Angel One | +7.34% |
| CarTrade Tech | +6.60% |
Broader NSE Market – Notable Losers
| Company | % Change |
| KEC International | -8.85% |
| Sterlite Technologies | -4.12% |
| Laurus Labs | -3.70% |
| TBO Tek | -3.61% |
| GE Shipping | -3.54% |
Bank Nifty: HDFC Bank and ICICI Bank were key contributors among private lenders, advancing 3.6% and 2.7%, respectively. However, weakness in select PSU banks and other constituents kept the index's gain below that of NIFTY.
Why Did We See Such a Strong Rally?
Strong Corporate Earnings
Quarterly earnings have supported the rally with companies reporting better-than-expected numbers have attracted buying interest.
Marico gained approximately 10% in the previous session following its earnings performance. Its Q2 FY27 consolidated profit increased 31% year-on-year, while revenue grew 13% which nudged investors to price the stock higher.
Cooling Crude Oil Prices Hold
Brent crude has not rallied back aggressively after declined approximately 7% ; the recovery still has only $110..
The earlier decline provided relief to market participants, particularly given India's dependence on imported crude as lower oil prices can support:
- India's import bill and current account.
- Inflation and corporate input costs.
- Oil-consuming sectors, including aviation, paints and consumer businesses.
- Overall investor sentiment towards Indian equities.
However, geopolitical developments remain a risk to this recovery.
Foreign Investors Are Returning
One of the more encouraging developments is the change in FPI positioning. Foreign portfolio investors were net buyers in four of the previous five sessions, suggesting that overseas investors are seeing opportunities in Indian equities again. SEBI’s proposals may also have a part; look out for an article around this shortly.
Expectations of potentially favourable long-term capital gains tax changes have also been cited as a sentiment-supporting factor. This should be treated as an expectation, not an announced policy change.
Banking and Financial Stocks Lead
Financials gained 1.8%, while private banks advanced 2%. HDFC Bank and ICICI Bank, which together account for nearly 20% of NIFTY 50, gained 3.6% and 2.7%, respectively. Improving earnings expectations and more attractive valuations in private lenders are helping support the benchmark indices.
Domestic Consumption and Sectoral Participation
FMCG, automobiles, cement and realty stocks also contributed to Tuesday's gains.
Thirteen of the sixteen major sector indices advanced during the session.
The 8-Session Rally: How Significant Is It?
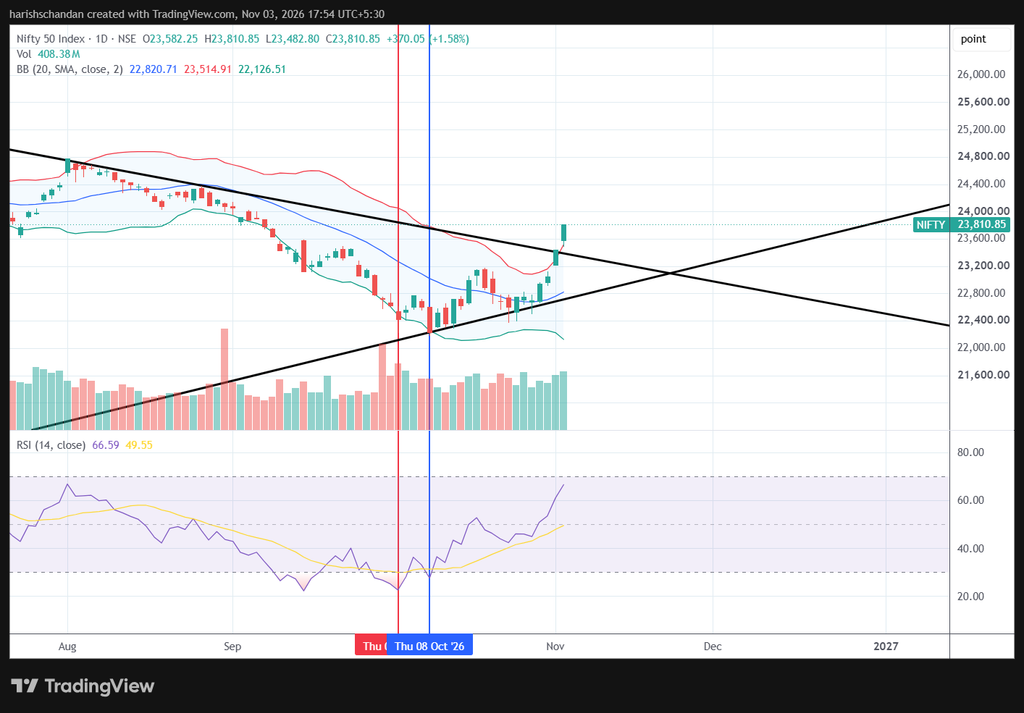
NIFTY 50 closed at 22,600 on 23 October 2026. It reached 23,810.85 on 3 November.
| Particulars | Performance |
| Starting level (23 October) | 22,600 |
| Closing level (3 November) | 23,810.85 |
| Absolute gain | 1,210.85 points |
| Percentage appreciation | +5.36% |
The NIFTY's four consecutive positive sessions have been particularly strong. Almost the entire eight-session recovery has been concentrated in these latest four sessions.
What Stands In This Rally?
Three observations deserve attention.
The Rally Is Being Supported by Heavyweight Stocks
HDFC Bank, ICICI Bank, Bharti Airtel and consumer-facing stocks have contributed to the benchmark recovery. Reliance Industries' exceptional 11.60% gain on 2 November also provided substantial support to the previous session's rally. However, Reliance slipped on 3 November, showing that buying is rotating between sectors rather than every heavyweight moving higher together.
Bank Nifty Is Still Lagging the Broader Benchmark
While NIFTY gained 1.58%, Bank Nifty advanced only 0.98% despite strong buying in HDFC Bank and ICICI Bank. This is something worth monitoring. As we have maintained earlier too, a sustained market advance would be an even better supported by broader participation from banking constituents.
Smallcaps Are Yet to Catch Up
The NIFTY Smallcap 250 gained only 0.42%, against a 1.58% rise in NIFTY. This suggests that investors are still showing a preference for relatively established and liquid companies over the broader Smallcap universe. The rally is positive, but its quality needs further confirmation.
6. What Next fo Investors?
| Indicator | What We Should Monitor |
| NIFTY 50 | Sustaining above 23,800 |
| Bank Nifty | Improving participation from PSU and private banks |
| Midcaps | Continuation of relative strength |
| Smallcaps | Improvement in breadth and participation |
| FPI flows | Whether buying continues |
| Crude oil | Whether prices remain under control |
| Q2 earnings | Whether earnings justify the recovery |
| India VIX | Whether volatility begins declining |
The next few sessions will be critical in determining whether this is a sustainable recovery or a sharp relief rally following the previous weakness.
Assessment
Whilst The market has delivered an encouraging recovery. The combination of improving earnings, lower crude prices, renewed foreign buying and strength in financials has helped restore investor confidence.
However, we should not overlook the difference between the benchmark indices and the broader market.
NIFTY and SENSEX are approaching important psychological levels, while Bank Nifty and smallcaps are still showing relatively weaker participation.
The 8-session advance of 5.36% is significant, but historical comparisons suggest that substantially larger advances have generally required sustained participation over longer periods.
Our view: The near-term market structure has improved. However, chasing the rally after four consecutive strong sessions may not offer an attractive risk-reward proposition across all stocks. Earnings, valuations, institutional flows and broader market participation will determine whether this recovery can develop into a more durable uptrend.
Indian Stock Market Analysis – 03 November 2026: NIFTY Rallies 1.58%, SENSEX Gains 1.62%; Derivatives Positioning in Focus
Indian equity markets extended their recovery on Tuesday, with NIFTY 50 gaining 370.05 points (1.58%) and SENSEX advancing 1,225.07 points (1.62%).
Buying interest was visible across financials, FMCG, automobiles and consumer-facing stocks. NIFTY also moved above the 23,800 level highlighted in our previous market analysis.
However, the recovery remains uneven. Bank Nifty and smallcaps underperformed the benchmark indices, making broader market participation an important factor to watch.
Our analysis covers the market performance, leading stocks, reasons behind the rally, derivatives positioning, Open Interest (OI), PCR and comparisons with previous major market advances.
Market Closing Snapshot – 03 November 2026
| Index | Closing Level | Change | % Change |
| NIFTY 50 | 23,810.85 | +370.05 | +1.58% |
| SENSEX | 76,917.85 | +1,225.07 | +1.62% |
| BANK NIFTY | 55,540.05 | +537.85 | +0.98% |
| NIFTY MIDCAP 100 | 58,596.25 | +612.85 | +1.06% |
| NIFTY SMALLCAP 250 | 17,061.65 | +70.65 | +0.42% |
NIFTY and SENSEX led the recovery, while smallcaps gained just 0.42%. The difference indicates a preference for large, liquid companies rather than an equally strong recovery across the broader market.
NIFTY 50 – Highest Gainers and Losers
Top Gainers
| Company | % Change |
| BSE Ltd | +5.03% |
| Nestlé India | +4.47% |
| Tata Consumer | +4.29% |
| Asian Paints | +3.99% |
| Bharti Airtel | +3.77% |
Top Losers
| Company | % Change |
| Power Grid | -3.04% |
| SBI | -1.70% |
| ONGC | -1.13% |
| Adani Enterprises | -0.84% |
| Tata Steel | -0.49% |
Broader Market – Notable Gainers
| Company | % Change |
| Balrampur Chini Mills | +10.22% |
| Marico | +8.23% |
| Trident | +7.61% |
| Angel One | +7.34% |
| CarTrade Tech | +6.60% |
Broader Market – Notable Losers
| Company | % Change |
| KEC International | -8.85% |
| Sterlite Technologies | -4.12% |
| Laurus Labs | -3.70% |
| TBO Tek | -3.61% |
| GE Shipping | -3.54% |
Why Did the Indian Stock Market Rally?
The rally was supported by a combination of improving earnings, crude oil movements, foreign investor activity and buying in heavyweight stocks.
Corporate earnings: Marico's Q2 FY27 consolidated profit increased 31% year-on-year, while revenue grew 13%. Better-than-expected earnings have continued to attract buying interest in select companies.
Crude oil: Brent crude declined approximately 7% in the previous session before recovering around 1% to $106 per barrel on Tuesday. A sustained decline in crude prices would benefit India's import bill, inflation outlook and oil-consuming industries.
Foreign investor participation: FPIs were net buyers in four of the previous five sessions. This change in positioning has helped improve sentiment, although sustained inflows will be important to confirm the trend.
Banking stocks: HDFC Bank and ICICI Bank gained 3.6% and 2.7%, respectively. Financials and private banks were among the important contributors to the benchmark recovery.
Sectoral participation: FMCG, automobiles, cement and realty stocks also advanced. Thirteen of the sixteen major sector indices recorded gains, indicating participation beyond a handful of heavyweight stocks.
Research Analyst Details
S. Harish Chandan
SEBI Registered Research Analyst
SEBI Registration No.: INH000012768
BSE Enlistment No.: 5826
Website: https://raharishchandan.com
Contact: +91 88944 66882
Disclaimer
This market commentary is prepared for informational and analytical purposes only. It is not an offer, solicitation or recommendation to buy, sell or hold any securities or financial instruments.
The views and observations expressed are based on publicly available information and market data considered at the time of preparation. Market conditions can change, and past performance is not indicative of future results.
Investors should conduct their own due diligence and consult their financial advisers before making investment decisions. Derivatives and leveraged trading involve substantial risk and may not be suitable for all investors.
Please refer to the applicable research disclosures and terms published on our website.
Reference Websites for further data & study:
NSE India – Live Equity Market: https://www.nseindia.com/market-data/live-equity-market
NSE India – Historical Index Data: https://www.nseindia.com/reports-indices-historical-index-data
NSE India – Participant-wise Open Interest: https://www.nseindia.com/all-reports-derivatives
NSE India – Option Chain: https://www.nseindia.com/option-chain
NSE Indices – NIFTY 50 Factsheet: https://www.niftyindices.com/Factsheet/ind_nifty50.pdf
NSE India – Corporate Filings and Financial Results: https://www.nseindia.com/companies-listing/corporate-filings-financial-results
Reliance Industries – Investor Relations: https://www.ril.com/investors
BSE India – Corporate Announcements: https://www.bseindia.com/corporates/ann.html
SEBI – Official Website: https://www.sebi.gov.in/
NSDL – FPI Investment Statistics: https://www.fpi.nsdl.co.in/web/Reports/Latest.aspx
CDSL – FPI Statistics: https://www.cdslindia.com/Publications/ForeignPortInvestor.html
PPAC (Petroleum Planning & Analysis Cell), Ministry of Petroleum & Natural Gas: https://ppac.gov.in/
Ministry of Commerce & Industry – Trade and Economic Data: https://commerce.gov.in/
RBI – Database on Indian Economy: https://data.rbi.org.in/
