Prepared by S Harish Chandan | SEBI Registered Research Analyst
Pre Market Report – 05 November 2026: FIIs Continue Buying, US Markets Rally; NIFTY 24,000 in Focus
Prepared by S Harish Chandan | SEBI Registered Research Analyst
Market Outlook: Positive Global Cues, NIFTY continues to roar
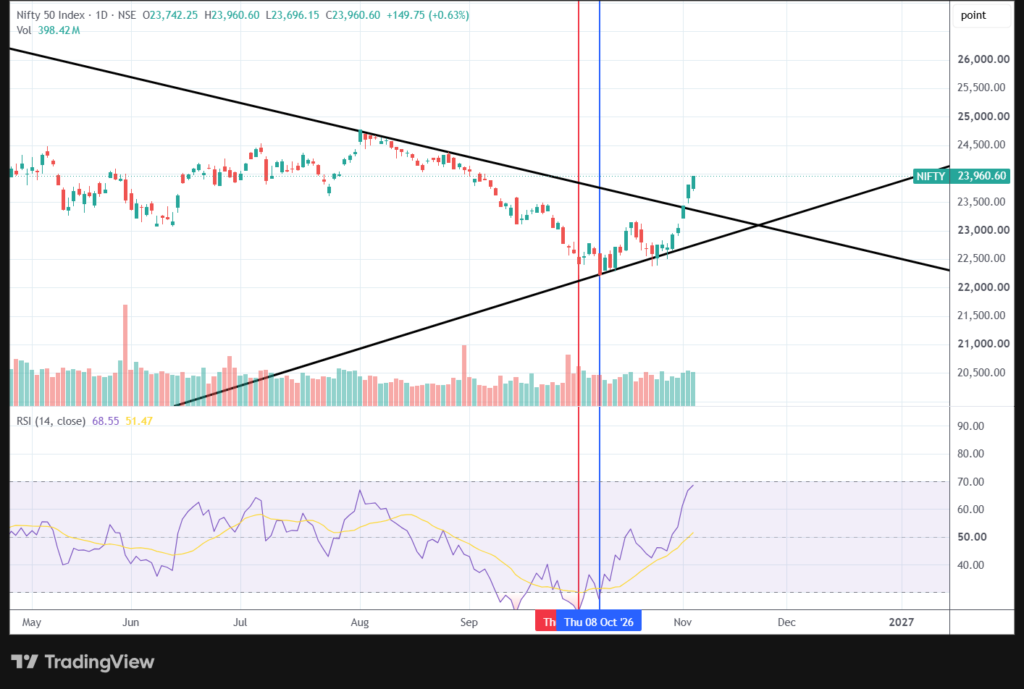
Indian markets enter Thursday's session with improving global cues; we expected a mild consolidation as the markets opened and a continued bullish outlook and that is how 04 Nov 2026 turned out; reaching out to the 24,000 levels.
As of US Market Close, the SGX NIFTY stands at 24,385; up from 23,975 (+1.7%) levels at Indian market close time; a clear sign of strength; we will update the latest SGX NIFTY level in the comments near the market open time tomorrow.
The winning streak has lasted five sessions now; while Midcap and Smallcap stocks outperformed the benchmark. FIIs continued their buying activity, India VIX declined, and market participation improved – all significantly positive signs.
Overnight, US markets rallied sharply following the US midterm election outcome – apparently it is something that happens following Midterms giving power to Democrats in both the houses; there are of course; a lot of things riding on this. The Dow gained nearly 3%, while the S&P 500 and Nasdaq advanced around 1.7%. Crude oil also witnessed a significant decline.
Levels to watch for on the upside would be – 24387, 24774 & 24900
The broader short-term trend remains positive, but traders should avoid chasing a gap-up opening without first assessing whether the market can sustain those levels.
FII and DII Activity: Foreign Buying Continues
Institutional activity remains one of the most important factors to track.
Cash-market activity – 04 November 2026
| Category | Buy | Sell | Net |
| FII/FPI | ₹21,607 Cr | ₹14,323 Cr | +₹7,284 Cr |
| DII | ₹16,393 Cr | ₹20,105 Cr | -₹3,712 Cr |
| Combined | ₹38,000 Cr | ₹34,428 Cr | +₹3,572 Cr |
FIIs have now been net buyers for four consecutive sessions. Their cumulative net buying over the last five sessions stands at approximately ₹19,890 crore.
DIIs, on the other hand, have been net sellers over the same five-session period, with cumulative net selling of approximately ₹6,676 crore.
The broader 20-session picture is more balanced: FIIs have been net sellers, while domestic institutions have continued to provide substantial support.
What stands out: Foreign buying is returning, but we should not confuse cash-market purchases with a complete reversal in their derivatives positioning.
FII index futures positioning
| Participant | Net position (contracts) | Change in net position |
| FII | -1,85,979 | +16,778 |
| DII | +42,318 | -786 |
| Proprietary | -6,132 | -12,307 |
| Clients | +1,49,793 | -3,685 |
FIIs remain net short in index futures, with 2,20,818 short contracts against 34,839 long contracts. However, their net short position reduced by 16,778 contracts during the previous session. This indicates a reduction in bearish exposure, although FIIs have not yet moved to a net-long position.
This is an important distinction when interpreting the recent cash-market buying.
India VIX: Volatility Declines
India VIX closed at approximately 15.19, declining 3.37% from the previous session.
Percentage change -3.37%
The decline in India VIX is supportive of the ongoing recovery. It indicates that the market's implied volatility expectations have moderated.
Global Markets: Wall Street Leads the Recovery
US markets rallied following the midterm election results, with investors responding positively to the prospect of greater political checks and reduced policy uncertainty.
US market closing performance
| Index | Change |
| Dow Jones | +2.97% |
| S&P 500 | +1.72% |
| Nasdaq Composite | +1.77% |
The rally was broad, although technology performance remained mixed. Concerns around AI infrastructure spending, data-centre investment and potential regulatory changes continued to weigh on some semiconductor and data-centre stocks.
For today's Indian session, the strong US close and the movement in crude oil are more supportive than the mixed Asian performance of the previous day.
Commodities and Currency
The sharp decline in crude oil is a significant development for Indian markets.
| Asset | Latest available reference |
| Brent crude | $94.62/barrel |
| Gold 999 – India benchmark | ₹1,41,228/10g |
| Silver 999 – India benchmark | ₹1,86,277/kg |
| USD/INR | ₹94.74 |
Brent crude declined approximately 8.7% on Wednesday, reaching its lowest level since August 31.
The fall followed developments around the US midterm elections and expectations that the new political balance could constrain further military escalation and encourage negotiations concerning the Iran conflict.
For India, lower crude prices can help reduce pressure on the import bill, inflation and corporate input costs.
Gold and silver prices above are the latest available Indian bullion benchmark readings from 04 November at 03:00 IST. Local retail prices may differ.
The USD/INR reference is the latest available exchange-rate reading for 03 November; it should not be treated as a live opening quote for today.
Cryptocurrency Market
Digital assets also saw positive movement over the latest 24-hour period.
| Cryptocurrency | Indicative price | 24-hour change |
| Bitcoin | ₹75.70 lakh | +3.43% |
| Ethereum | ₹2.27 lakh | +4.92% |
| BNB | ₹67,380 | +2.17% |
Crypto markets are not a direct indicator of Indian equity market direction, but they remain useful as part of the broader global risk-sentiment picture.
Sectoral Performance: Realty, Media and Metals Lead
The previous session saw broad-based buying across sectoral indices.
| Sector | 04 Nov change |
| NIFTY Media | +5.15% |
| NIFTY Realty | +2.85% |
| NIFTY Metal | +2.80% |
| NIFTY Consumer Durables | +2.04% |
| NIFTY Oil & Gas | +1.54% |
| NIFTY IT | -1.50% |
Realty, Media and Metal stocks led the advance. IT remained the notable laggard, with TCS, HCL Technologies and Infosys under pressure.
For today's session, crude oil's sharp decline could influence Oil & Gas, upstream producers, aviation and other fuel-sensitive businesses. The actual stock-level impact will depend on company-specific factors and the direction of crude prices through the session.
Midcap and Smallcap Review
The broader market continued to outperform the benchmark indices.
| Index | Closing level | Change |
| NIFTY 50 | 23,960.60 | +0.63% |
| NIFTY 500 | 22,769.20 | +1.11% |
| NIFTY MIDCAP 100 | 59,505.50 | +1.55% |
| NIFTY SMALLCAP 100 | 19,026.40 | +2.00% |
| NIFTY SMALLCAP 250 | 17,398.35 | +1.97% |
Smallcaps outperformed Midcaps, while both segments gained substantially more than NIFTY 50.
Notable Midcap gainers
- NLC India: +8.97%
- Exide Industries: +6.43%
- Hindustan Copper: +6.37%
- BHEL: +5.96%
- Lodha Developers: +5.77%
Notable Smallcap gainers
- Gujarat Mineral Development: +10.08%
- Redington: +9.47%
- IIFL Finance: +7.48%
- Godawari Power: +7.32%
- Jyoti CNC: +7.10%
The improvement in broader-market participation is encouraging at the moment; as we have spoken about earlier as well, their continuance will be necessary for the market to sustain any higher levels.
Derivatives Positioning: NIFTY 50
The latest available end-of-day option-chain data relates to the 09 November expiry.
| Parameter | Reading |
| NIFTY close | 23,960.60 |
| Total Call OI | 14.22 crore units |
| Total Put OI | 15.27 crore units |
| PCR (OI) | 1.07 |
| Max Pain | 23,800 |
| Highest Call OI | 25,000 |
| Highest Put OI | 23,000 |
| Near-term Call concentration | 24,000 |
| Near-term Put concentration | 23,500 |
What does the options data indicate?
- The full-chain PCR of 1.07 indicates higher Put OI than Call OI.
- The 24,000 strike remains an important near-term Call-side concentration.
- The 23,500 strike is an important Put-side reference.
- Max Pain at 23,800 is below the current spot level.
- The 24,000 zone will be important to watch if the market opens higher.
The overall structure is not bearish. However, a positive PCR should not be interpreted as a guaranteed bullish signal. The behaviour of premiums, fresh OI additions and unwinding around the ATM strikes will be important.
Derivatives Positioning: BANK NIFTY
The latest available end-of-day option-chain data relates to the 23 November expiry.
| Parameter | Reading |
| BANK NIFTY close | 55,913.60 |
| Total Call OI | Approximately 4.6 lakh contracts |
| Change in Call OI | +19,400 |
| Total Put OI | Approximately 4.6 lakh contracts |
| Change in Put OI | +26,600 |
| PCR (OI) | 0.99 |
| Max Pain | 55,700 |
| Major Call OI concentration | 58,000 |
| Major Put OI concentration | 55,000 |
The Put-side additions were higher than Call-side additions during the previous session.
Around the prevailing price, the 56,000 Call strike saw additions of approximately 45,400 contracts, while the 55,000 Put strike added approximately 59,900 contracts.
Stocks and Earnings to Watch Today
The September-quarter earnings calendar remains busy.
Companies scheduled to announce or consider their results on 05 November include:
- Mahindra & Mahindra
- Bharti Airtel
- Life Insurance Corporation of India
- Titan Company
- ONGC
- Britannia Industries
- Samvardhana Motherson International
- Bharat Forge
- Glenmark Pharmaceuticals
- Mphasis
- Berger Paints
- Thermax
FIIs continue to buy in the cash market, their index futures short exposure has reduced, India VIX has eased and broader-market participation has improved.
The overnight US rally and sharp correction in crude oil provide additional support to sentiment.
However, we should not overlook the fact that NIFTY has already advanced sharply over five consecutive sessions. A strong opening does not automatically mean that the entire session will remain positive.
Our short-term outlook remains positive. The 24,000–24,100 zone is now the immediate area to watch. The market's ability to sustain above this region, rather than merely touch it, will be important.
We would prefer to see a stable opening, sustained buying and continued participation from Midcap and Smallcap stocks. Traders should remain disciplined and avoid chasing sharp opening moves.
What we saw and What to watch today – 05 November 2026
- Whether GIFT NIFTY sustains its positive indication of 24,385 and translates into a strong opening for NIFTY.
- Whether NIFTY can decisively cross and sustain above 24,000, with 24,387, 24,774 and 24,900 as the next upside levels to monitor.
- We saw realty, Media and Metal stocks, alongside any recovery in IT.
- The impact of the sharp decline in Brent crude on Oil & Gas, aviation and other crude-sensitive sectors is seen – it is still an important factor
- Global market cues, US Treasury yields, Asian market movements and developments surrounding the US midterm election outcome.
- Whether FII cash-market buying – will it continues and how do their net short positions in index futures reduce further.
- Whether India VIX remains below 16, indicating continued moderation in expected volatility.
- Fresh Call and Put additions around NIFTY 24,000 and 23,500, and BANK NIFTY 56,000 and 55,000.
- Whether Midcap and Smallcap outperformance need to continue
- Quarterly earnings announcements from M&M, Bharti Airtel, LIC, Titan, ONGC, Britannia and other companies reporting today.
Research Analyst Details
S. Harish Chandan
SEBI Registered Research Analyst
SEBI Registration No.: INH000012768
BSE Enlistment No.: 5826
Website: https://raharishchandan.com
Contact: +91 88944 66882
Disclaimer
This market commentary is prepared for informational and analytical purposes only. It is not an offer, solicitation or recommendation to buy, sell or hold any securities or financial instruments.
The views and observations expressed are based on publicly available information and market data considered at the time of preparation. Market conditions can change, and past performance is not indicative of future results.
Investors should conduct their own due diligence and consult their financial advisers before making investment decisions. Derivatives and leveraged trading involve substantial risk and may not be suitable for all investors.
Please refer to the applicable research disclosures and terms published on our website.
Reference Websites for further data & study:
NSE India – Live Equity Market: https://www.nseindia.com/market-data/live-equity-market
NSE India – Historical Index Data: https://www.nseindia.com/reports-indices-historical-index-data
NSE India – Participant-wise Open Interest: https://www.nseindia.com/all-reports-derivatives
NSE India – Option Chain: https://www.nseindia.com/option-chain
NSE Indices – NIFTY 50 Factsheet: https://www.niftyindices.com/Factsheet/ind_nifty50.pdf
NSE India – Corporate Filings and Financial Results: https://www.nseindia.com/companies-listing/corporate-filings-financial-results
Reliance Industries – Investor Relations: https://www.ril.com/investors
BSE India – Corporate Announcements: https://www.bseindia.com/corporates/ann.html
SEBI – Official Website: https://www.sebi.gov.in/
NSDL – FPI Investment Statistics: https://www.fpi.nsdl.co.in/web/Reports/Latest.aspx
CDSL – FPI Statistics: https://www.cdslindia.com/Publications/ForeignPortInvestor.html
PPAC (Petroleum Planning & Analysis Cell), Ministry of Petroleum & Natural Gas: https://ppac.gov.in/
Ministry of Commerce & Industry – Trade and Economic Data: https://commerce.gov.in/
RBI – Database on Indian Economy: https://data.rbi.org.in/
