Quick review of Indian Stock Market Analysis - 27 Oct 2026 - NIFTY -
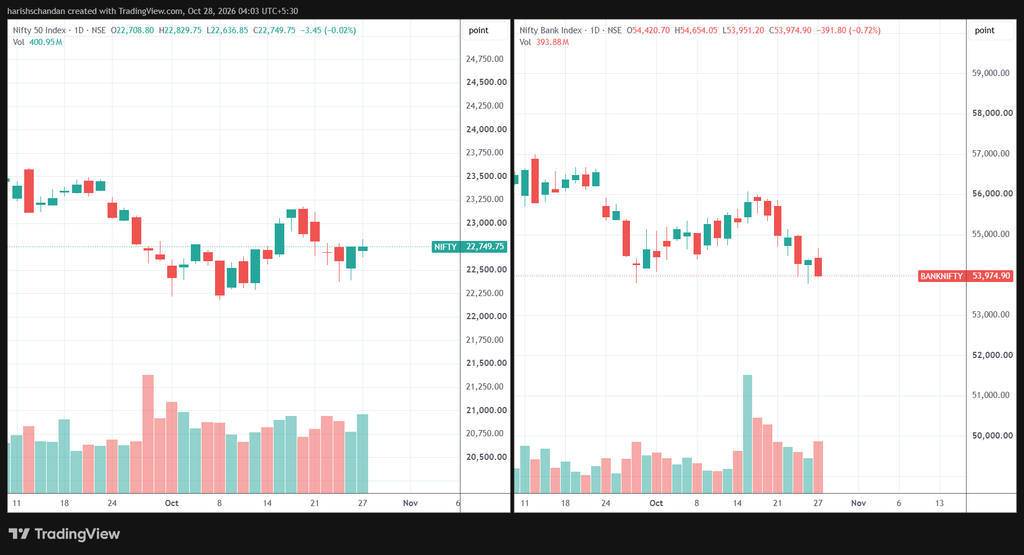
The Indian stock market ended Tuesday, 27 October 2026, expectedly gave an almost unchanged close, providing moves up and down within a range providing a perfect Options seller's Tuesday expiry. The NIFTY 50 closed at 22,749.75, down 3.45 points, while the Sensex finished at 73,598.67, a marginal decline of 8.08 points. The headline numbers, however, do not tell the full story of the session. MIDCAP stocks however showed strength ending 1% higher on the day while NIFTY SMALLCAP 250 was even more exuberant with a 2.19% gain.
Banking stocks remained under pressure, while buying in several broader-market and sectoral indices helped offset weakness in the benchmarks. Auto, pharma, realty and media stocks were among the stronger pockets of the market.
For traders, what would be interesting and keenly observed is whether the strength outside the headline indices can sustain itself while banking stocks remain weak and investors assess elevated crude oil prices and the upcoming US Federal Reserve decision.
1. Market closing snapshot
| Index / Indicator | Closing value | Change |
|---|---|---|
| NIFTY 50 | 22,749.75 | -3.45 points (-0.02%) |
| BSE Sensex | 73,598.67 | -8.08 points (-0.01%) |
| Bank Nifty | 53,974.90 | -391.80 points (-0.72%) |
| India VIX | 16.40 | -0.76 (-4.41%) |
| NIFTY Midcap 100 | 57,029.90 | +564.50 (+1.00%) |
| NIFTY Smallcap 250 | 16,933.70 | +363.20 (+2.19%) |
The contrast between Bank Nifty and the broader market also deserves attention. While Bank Nifty lost 0.72%, the NIFTY Midcap 100 gained 1% and the NIFTY Smallcap 250 advanced 2.19%. This suggests that buying was not limited to a handful of heavyweight stocks, although a single session is not enough to establish a lasting change in market direction.
2. Why the NIFTY closed flat despite broader-market buying
The NIFTY moved through a volatile session before finishing marginally lower. Selling in banking and IT stocks offset gains in other sectors, leaving the benchmark with very little net movement by the close.
The sectoral performance was more revealing than the headline index:
| Sector | Change |
|---|---|
| Media | +3.66% |
| Pharma | +1.91% |
| Realty | +1.94% |
| Auto | +1.48% |
| IT | -0.26% |
| Financial Services | -0.59% |
| Bank Nifty | -0.72% |
Media, pharma, realty and auto stocks attracted buying interest. In contrast, banking and financial stocks weighed on the headline indices. This divergence matters because a flat NIFTY can conceal substantial differences in the performance of individual sectors.
For traders, sector selection and stock-specific price action may therefore be more informative than taking a directional view based only on the NIFTY's closing percentage.
3. India VIX falls: Has market anxiety eased?
India VIX closed at 16.40, down 4.41% and the decline indicates that the market's measure of expected near-term volatility eased during the session. It does not, by itself, mean that the market has become bullish or bearish.
India VIX reflects expected volatility derived from NIFTY options. It does not indicate whether the NIFTY will rise or fall.
The combination of a lower VIX and a nearly unchanged NIFTY is worth monitoring. If the VIX continues to ease while the index holds its important price levels, traders may see more stable conditions for directional strategies. If volatility rises again alongside weakness in banking stocks, that would be a different signal.
For now, the VIX reading should be considered alongside price action, market breadth and changes in derivatives positioning rather than used as a standalone trading signal.
4. NIFTY and Bank Nifty options: Where is open interest concentrated?
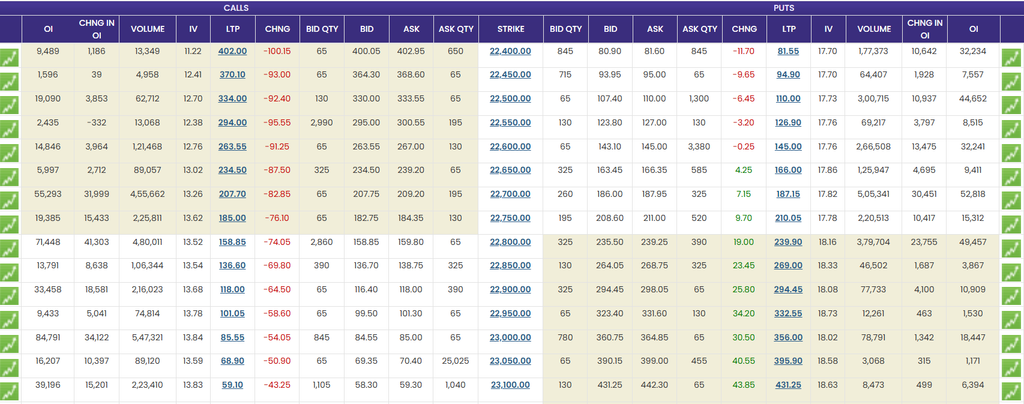
Options open interest provides a snapshot of outstanding positions at different strike prices. It can help traders identify levels that may attract attention, but it should not be interpreted as a guarantee of support or resistance.
The following figures relate specifically to the 27 October 2026 expiry, not to a future trading session.
| Derivatives indicator | NIFTY | Bank Nifty |
|---|---|---|
| Highest call OI | 22,800 | 56,000 |
| Highest put OI | 22,750 | 54,000 |
| Max pain | 22,750 | 54,900 |
| Put-call ratio (OI) | 1.03 | 0.80 |
NIFTY: 22,750–22,800 in focus
The 22,800 strike had the highest call open interest, while the highest put open interest was at 22,750. Max pain was also reported at 22,750.
For that expiry, these strikes were close to the NIFTY's closing level and formed a useful reference for understanding the day's derivatives positioning. However, the expiry-day snapshot should not be carried forward as a live support-and-resistance map for the next session.
Bank Nifty: Banking weakness remains relevant
Bank Nifty closed at 53,974.90, down 391.80 points. Its options data showed the highest call OI at 56,000, the highest put OI at 54,000 and max pain at 54,900 for the same expiry.
The put-call ratio of 0.80 was lower than NIFTY's reported 1.03. This indicates a relatively greater concentration of call open interest than put open interest across the relevant Bank Nifty chain, but it is not a standalone bearish signal.
What should traders watch next? Use the current expiry's option chain, changes in open interest, the underlying index's price action and volume together. Yesterday's largest OI strikes can become less relevant as positions are closed and new contracts especially reflect the next month of November.
5. Upcoming IPOs: Issues opening and closing this week
The primary market remains active, with several mainboard issues scheduled around the end of October. The calendar below reflects published schedules available on 27 October 2026. Investors should check the latest exchange notices and offer documents before applying.
| IPO | Segment | Issue period |
|---|---|---|
| EAAA India Alternatives | Mainboard | 26–28 October |
| BLS Polymers | Mainboard | 27–29 October |
| SFC Environmental Technologies | Mainboard | 27–29 October |
| M. K. Sons Fine Jewels | Mainboard | 28–30 October |
| Bombay Coated and Special Steels | Mainboard | 29 October–2 November |
Dates are based on IPO calendars updated on 27 October 2026. Issue schedules can change.
IPO activity can attract investor attention and redirect some capital towards new offerings. However, the number of active IPOs does not tell us whether the secondary market is likely to rise or fall.
Investors evaluating these issues should focus on the offer document, business model, financial performance, valuation, use of proceeds and risks. Grey market premiums, where reported, are unofficial and do not guarantee listing gains.
6. Crude oil and the US Federal Reserve: External factors to monitor
Crude oil remained elevated, with Brent trading around $115 per barrel in reports covering the session. Investors were also cautious ahead of the US Federal Reserve's policy decision scheduled for later in the week.
For India, a sustained rise in crude oil prices can increase the import bill, place pressure on inflation and affect the cost structures of oil-consuming businesses. The impact on individual companies varies depending on their ability to pass on higher costs and their exposure to energy prices.
The Federal Reserve decision is another event worth monitoring because changes in interest-rate expectations can influence global risk appetite, currency movements and foreign portfolio flows.
These are factors to watch, not predictions of the next market move. Their actual influence will depend on the information released and how investors respond to it.
7. What does this mean for the next trading session?
The 27 October close leaves a mixed picture rather than a clear directional signal.
- NIFTY: The benchmark ended almost unchanged. The next session's price action will be more useful than the small closing decline in isolation.
- Bank Nifty: Its 0.72% fall makes banking stocks an important area to monitor. A recovery or further weakness could influence the headline indices.
- Broader markets: Midcap and smallcap gains were stronger than the headline indices. Traders should watch whether this participation continues.
- India VIX: The decline points to lower measured volatility, but does not establish a bullish trend.
- Options OI: The 27 October expiry levels are historical references. Use the latest chain before drawing conclusions about current positioning.
- External events: Crude oil and the Federal Reserve decision remain relevant to the risk environment.
My reading of the session is straightforward: the headline indices were largely flat, but the underlying market was not uniform. Strength in selected sectors and broader-market stocks was offset by weakness in banking and some large-cap names.
The next session needs to confirm whether this divergence continues or whether buying broadens enough to support the benchmark indices. Until then, it is sensible to avoid drawing a strong directional conclusion from a nearly unchanged NIFTY close.
Useful Market Research Resources
Readers can use the following resources to review market data and conduct their own analysis:
- Charts and Technical Analysis: TradingView India
- Options Chain and Open Interest: NSE Option Chain
- Historical Derivatives Data: NSE Derivatives Reports
- Official Index and Market Data: NSE India
- Upcoming IPOs and Public Issues: NSE IPO Information
- Investor Education and Regulatory Information: SEBI Investor Website
These links are provided for reference and independent research. Market data may change during trading hours. Readers should verify time-sensitive information from the relevant official source before making investment or trading decisions.
Article by -
S Harish Chandan | SEBI Registered Research Analyst
SEBI Registration No.: INH000012769 | BSE Enlistment No.: 5826
The information and analysis presented in this article are for research and informational purposes only. Market data, technical indicators, forecasts and opinions are based on information believed to be reliable at the time of publication; however, accuracy and completeness are not guaranteed.
Securities-market investments are subject to market risks. Any analysis, price levels or market outlook should not be construed as a guarantee of returns or a promise of future performance. Past performance does not guarantee future results. Investors should independently assess risks and make decisions based on their financial objectives and risk tolerance.
Any material financial interest or conflict of interest relevant to a specific research report will be disclosed as applicable under SEBI regulations.
Registration granted by SEBI and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors.
For queries or grievances, contact: support@raharishchandan.com | +91 8894466882
Website: https://raharishchandan.com
